
Last reviewed: June 2026
Choosing between YNAB and Monarch Money comes down to one central question: do you want to actively direct every dollar before you spend it, or do you want software to track your spending automatically and surface patterns for you? Both apps charge a subscription fee, both connect to bank accounts, and both aim to improve financial awareness. The similarities largely stop there.
YNAB, short for You Need A Budget, is built on a zero-based budgeting framework that requires assigning every dollar of income to a spending category before the money goes out. Monarch Money leans on AI auto-categorization and aggregated bank data to give you a real-time view of where your money has already gone. You can compare more personal finance and AI budgeting tools in the AI finance tools directory.
This breakdown of ynab vs monarch money looks at how each method works in practice, where each app falls short, what each costs, and which type of user is a reasonable fit for each.
Key takeaways
- YNAB uses a zero-based approach that requires active daily engagement with budget categories.
- Monarch Money automates transaction categorization using AI, reducing the required daily effort.
- Both tools are paid subscriptions that offer free trials before committing.
- YNAB is well-suited for users focused on debt payoff or building new spending habits.
- Monarch Money is well-suited for users who want a consolidated view of net worth and passive spending trends.
How YNAB’s Give-Every-Dollar-a-Job Method Works
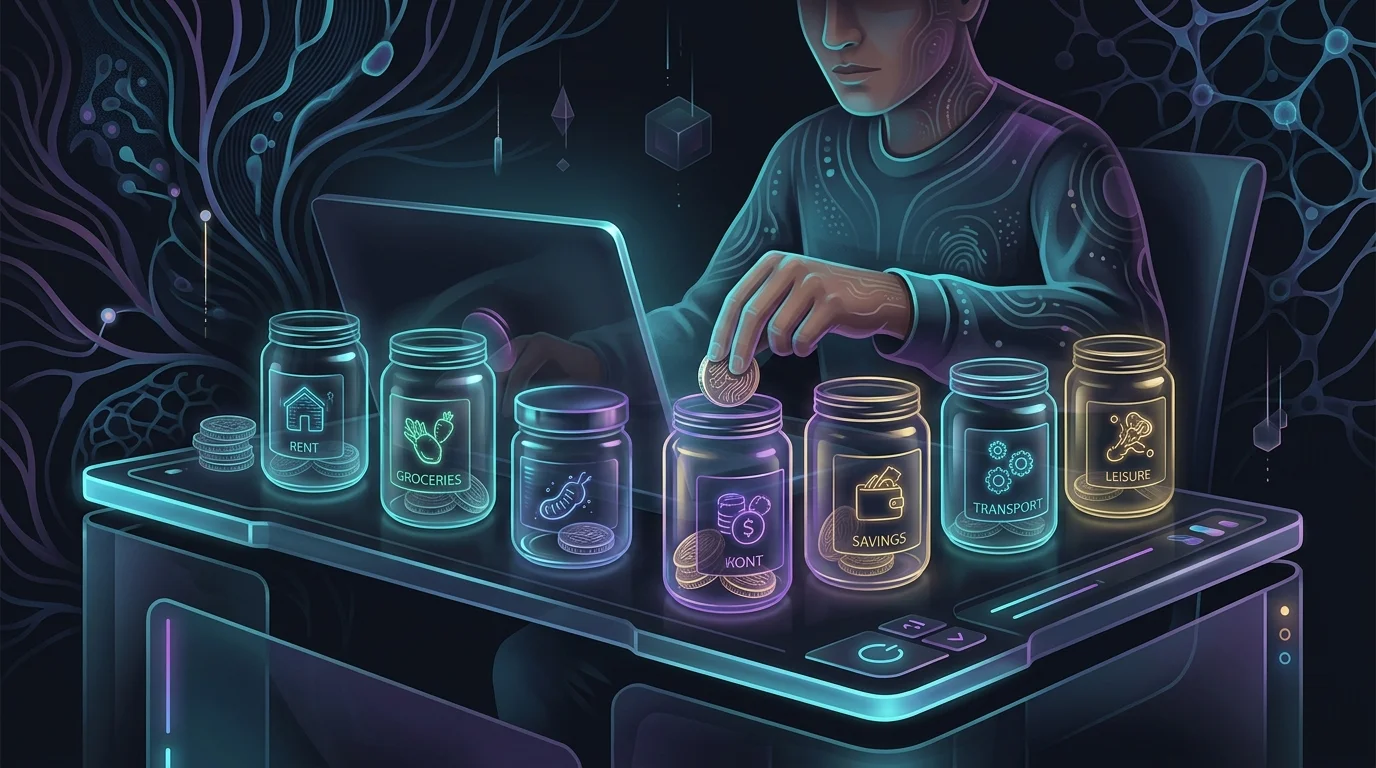
YNAB is organized around a set of rules that its founders have taught for years. The central principle is to assign every dollar you currently have to a job, whether that is rent, groceries, an emergency fund, or a debt payment. You do this before the money is spent, not after. The result is a budget that reflects intentional decisions rather than a log of past behavior.
The app connects to bank accounts for syncing, but it still expects you to review and approve each transaction, reassign categories when auto-categorization misses, and reconcile accounts regularly. This friction is intentional. YNAB operates on the premise that awareness of each transaction changes how you spend, and the manual review step is part of the method rather than a flaw in it.
- Assign income to categories before spending it
- Bank sync is available but manual review is part of the workflow
- Mobile app supports on-the-go transaction entry
- Includes an education library and active community forums
How Monarch Money Uses AI to Categorize and Track Spending
Monarch Money connects to bank accounts, credit cards, investment accounts, and loans, then uses AI to categorize incoming transactions automatically. The result is a unified dashboard where spending by category, net worth over time, and investment performance are visible without manually entering or approving each transaction. See the Consumer Financial Protection Bureau for official guidance.
The app includes budgeting tools alongside its tracking features, so you can set category limits and receive alerts when you approach them. But the default experience is passive: the software handles categorization and you check in at whatever frequency suits you. This is a meaningfully different relationship with your finances compared to YNAB’s active model.
Daily Effort: How Much Time Each App Actually Requires
YNAB users who follow the method as intended spend a few minutes per day reviewing transactions, categorizing new entries, and moving money between categories when plans change. The app rewards this habit with clarity about exactly what is available to spend in any given category. Users who connect accounts and then walk away often find the budget drifts from reality over time.
Monarch Money can operate with very little daily input. Once accounts are connected and default category mappings are reviewed, the app updates in the background. The trade-off is that AI categorization makes occasional errors, and if you are not reviewing transactions those errors accumulate and distort your spending picture. A weekly review is enough for most users to keep the data reasonably accurate.
Limitations and Trade-offs Worth Knowing Before You Choose
YNAB’s method is demanding. New users face a learning curve that some find steep enough to abandon before the system clicks. The app does not track investment accounts or net worth in the same depth that Monarch does, so users who want a single dashboard for total financial health will find gaps. The subscription cost can feel hard to justify for anyone who is not actively using the budgeting features every week.
Monarch Money’s AI categorization is convenient but not perfect. Categories can be misassigned, especially for irregular or unusual transactions. The zero-based discipline that some users credit for eliminating debt is not native to Monarch’s design. Users who need to change spending behavior may find that passive tracking does not create the same behavioral pressure that YNAB’s active method produces.
- YNAB: steeper learning curve, limited investment tracking depth, requires a consistent daily habit
- Monarch: occasional AI categorization errors, less behavioral pressure, passive by design
- Neither app is free after the trial period ends
- Switching apps after months of data requires manual export and re-import
ynab vs monarch money: Matching the Tool to Your Financial Goals
The ynab vs monarch money decision is largely a question of temperament and goal. Someone working through credit card debt or trying to build a savings habit from scratch is likely to get more traction from YNAB’s active method because the required engagement itself reinforces behavior change. The app has a clear internal logic that, once learned, is difficult to replicate in passive tools.
Someone who already has stable spending patterns and wants a dashboard to monitor net worth, investment accounts, and cash flow without daily input is a more natural fit for Monarch Money. The two apps are not direct substitutes. Some households use YNAB for core budgeting and a separate tracker alongside it for investment visibility, though managing two subscription tools adds both cost and complexity.
What to Check Before You Commit to Either App
Before choosing in the ynab vs monarch money comparison, consider what outcome you are actually trying to reach. If the goal is to stop overspending in specific categories this month, YNAB provides a tight feedback loop. If the goal is to understand your total financial picture across all account types, Monarch aggregates that more cleanly. Both offer free trials, so running each one for a few weeks with real account data is a practical way to test which workflow fits your habits before paying.
- Focused on changing spending behavior: try YNAB first
- Focused on monitoring your total financial picture passively: try Monarch first
- Both offer free trials worth using before subscribing
- Verify your specific bank connections are supported on each platform before committing
How these tools compare
| Tool | Pricing Model | Best For |
|---|---|---|
| YNAB | Paid subscription (free trial available) | Hands-on zero-based budgeting and debt payoff |
| Monarch Money | Paid subscription (free trial available) | Automated tracking and net worth monitoring |
Sources
- savings goal calculator at Investor.gov
- compound interest calculator on Investor.gov
- how cryptocurrency scams work
- further context: financial well-being assessment
Frequently asked questions
Is YNAB or Monarch Money free?
Neither is free after the trial period ends. Both charge a monthly or annual subscription fee. Check each app’s current pricing page for up-to-date rates, as amounts have changed over time.
Which app works better for paying off debt?
YNAB’s zero-based method is specifically designed to direct money toward priorities like debt payoff by requiring active category assignment before spending. Users focused on aggressive debt reduction often find the active structure useful for maintaining discipline.
Does Monarch Money have AI budgeting features?
Monarch Money uses AI primarily for automatic transaction categorization rather than forward-looking budget management. It can suggest category assignments and surface spending patterns, but it does not use the give-every-dollar-a-job approach that YNAB is built around.
Can I use both YNAB and Monarch Money at the same time?
Technically yes, but running two subscription apps adds cost and means managing financial data in two separate places. Most users settle on one based on whether they prefer active or passive money management.
Which app has better bank connectivity?
Both apps connect to major US banks, credit cards, and investment accounts. Coverage varies by institution and changes over time. Check each app’s list of supported institutions before subscribing to confirm your accounts are included.
Is the YNAB learning curve worth the effort?
For users committed to changing spending habits, most find the method worthwhile once the logic clicks. For users who want simple spending tracking without a methodology to internalize, Monarch is a lower-friction starting point.
Related guides
- Best Rocket Money Alternatives With AI in 2026
- Best Cleo Alternatives: AI Money Apps Like Cleo 2026
- Copilot Money vs Monarch Money: Which AI App Wins in
- Best Budgeting Apps for 2025: Pick by Style, Not by Star Rating
- Is Copilot Money Worth It in 2026? Honest Review
- Rocket Money vs Cleo: Best AI Money App for
- Is Rocket Money Worth It in 2026? An Honest Look
- Best AI Budgeting Apps for College Students
- Mental Health & Behavioral Finance
- Maximize Your Savings: Discover 5 AI Budget Tools for Personal Finance
- Best Money Management Systems for People with ADHD