
Last reviewed: June 2026
Drivers who put fewer than 7,500 miles on their car each year routinely pay the same flat premiums as commuters who drive two or three times as much. Traditional underwriting averages risk across a broad pool, which means low-mileage drivers often subsidize heavier users. Pay-per-mile and telematics-based apps address this by anchoring your premium to actual driving data.
The market for ai car insurance low mileage products has grown to include both pure pay-per-mile plans and behavior-scored policies that reward safe, infrequent driving. If you want to browse beyond the four apps covered here, you can compare more options in the AI insurance tools directory.
This article covers Metromile, Root, Mile Auto, and Clearcover, walking through how each prices coverage, what data it collects, and where each is well-suited for drivers under 7,500 miles a year.
Key takeaways
- Pay-per-mile plans from Metromile and Mile Auto split your cost into a fixed base rate plus a per-mile charge, which can lower total premiums for drivers who rarely use their car.
- Root uses a smartphone-based test period to score your driving behavior and may offer lower rates if you drive safely and infrequently.
- Mile Auto collects only monthly odometer photos rather than continuous GPS data, which suits drivers who want to limit data sharing.
- Clearcover uses AI underwriting to set flat-rate premiums quickly without requiring a telematics device, making it straightforward for low-mileage drivers who prefer not to be tracked.
- State availability varies significantly across all four apps, so confirming a provider operates in your state is the first practical step before comparing rates.
How AI Pricing Models Work for Low-Mileage Drivers
Conventional insurers set premiums using actuarial models that factor in age, vehicle type, credit score, and ZIP code. Mileage is often self-reported and rarely verified. AI-driven apps replace or supplement that with real driving data, collected through a physical dongle plugged into the car’s OBD-II port, a smartphone app running in the background, or periodic odometer snapshots.
The result is pricing that reflects actual road exposure. A driver putting 3,000 miles on a car each year presents a statistically different risk profile than one logging 15,000, and these apps are designed to capture that difference. For drivers shopping for ai car insurance low mileage options, the distinction between per-mile billing and behavior-based scoring is worth understanding before comparing quotes.
Metromile: Per-Mile Billing via a Physical Device
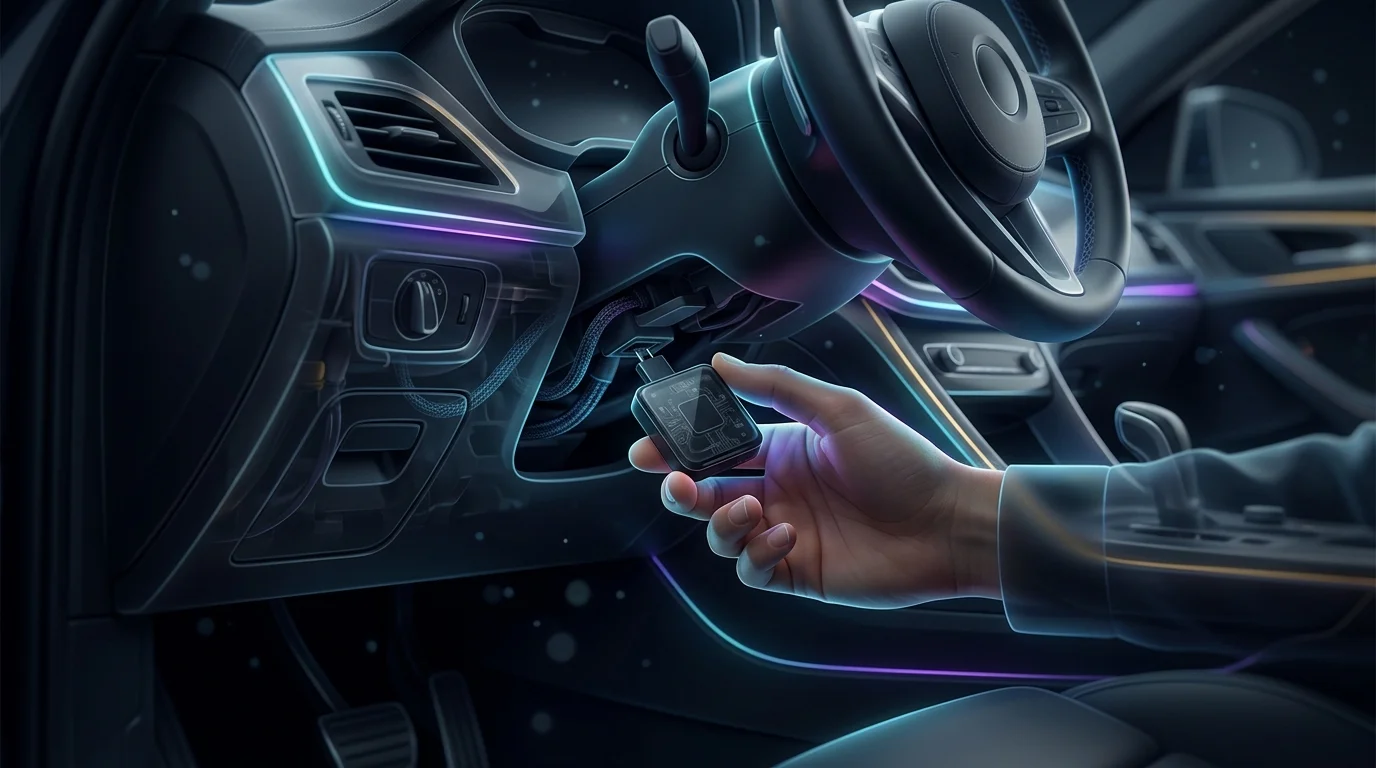
Metromile charges a fixed monthly base rate plus a per-mile fee for every mile you drive. To track mileage it ships a small device called the Pulse, which plugs into your car’s OBD-II port. The device transmits odometer and trip-level data to Metromile’s platform, where it feeds directly into billing calculations. See the National Association of Insurance Commissioners for official guidance.
Metromile is a practical option for urban drivers who rely mostly on transit or work remotely and drive only for errands. Because the per-mile charge applies only when you drive, months with very low mileage translate directly into lower bills. The trade-off is that the OBD-II device continuously reports vehicle data, and Metromile’s coverage does not extend to all states.
Root Insurance: Behavior-Based Scoring During a Test Drive
Root takes a different approach from standard ai car insurance low mileage plans. Instead of billing per mile, it uses a test-drive period, typically two to three weeks, during which its smartphone app monitors how you brake, accelerate, and turn, and what time of day you drive. At the end of the test period, Root generates a driving score and uses it to set your quote.
Low-mileage drivers who also drive carefully can score well under Root’s model. However, a driver who takes few trips but brakes hard may not see meaningful savings compared to traditional insurers. Root is available in more states than some competitors, which adds accessibility, but its savings depend on driving style as much as annual distance.
Mile Auto: Odometer Photos Instead of Continuous Tracking
Mile Auto also runs on a pay-per-mile model but avoids the continuous data collection that makes some drivers uncomfortable. Each month, policyholders submit a photo of their odometer through the app. Mile Auto calculates the monthly bill from that reported figure without tracking routes, speeds, or behavior.
This makes it one of the more privacy-conscious options among ai car insurance low mileage providers. The limitation is that the model relies on self-reported data rather than real-time telemetry, so the insurer cannot factor in behavioral risk signals the way device-based plans can. Coverage is available in a limited set of states.
Clearcover: Flat-Rate Digital Coverage Without Telematics
Clearcover positions itself as a digital-first insurer that uses AI to streamline underwriting and claims processing rather than to monitor driving habits. It offers flat-rate policies with no requirement for a device or background app tracking. The company’s AI tools are aimed at reducing administrative overhead and speeding up claims approvals, which it argues supports competitive pricing.
For low-mileage drivers who dislike the idea of behavioral monitoring, Clearcover offers a straightforward alternative. The premium will not drop if you drive fewer miles in a given month, but it will not increase either. Drivers who want a clean separation between their insurance cost and their driving data may find this structure simpler to manage.
Limitations and Trade-Offs Worth Knowing
Pay-per-mile policies can work against drivers who take occasional long trips. If your mileage spikes in a given month due to a road trip or a temporary change in routine, your bill rises with it. Metromile limits the miles billed per day on some plans, which softens the impact on longer drives, but specific terms depend on your plan and state.
Telematics apps also raise data privacy considerations. Continuous monitoring of your location and driving patterns creates a data record that could be accessed in legal contexts or shared under terms you may not have fully reviewed. Reading each app’s privacy policy before enrolling is worth the time.
- Savings over a flat-rate policy depend on what your current insurer charges, not just on your mileage alone.
- None of the four apps operates in all 50 states, which limits options for many drivers.
- Behavioral scoring through Root or Metromile may produce higher quotes for drivers with aggressive habits, even if they drive infrequently.
- Customer service quality and claims handling records vary and are worth checking through state insurance department complaint databases.
Matching the Right App to Your Driving Pattern
The most practical first step is to get a quote from your current insurer for a reduced-mileage classification if one exists, then compare it against quotes from these apps. Mileage alone does not determine savings; your driving profile, state of residence, vehicle type, and coverage requirements all factor in.
Drivers who prioritize privacy and maintain consistent low mileage may find Mile Auto or Clearcover a good fit. Drivers comfortable with behavioral monitoring and who drive carefully may benefit from Root. Drivers in urban areas who keep their car parked most of the time should look specifically at Metromile’s per-mile structure.
How these tools compare
| App | Pricing Model | Suited For |
|---|---|---|
| Metromile | Pay-per-mile (base rate + per-mile fee) | Urban drivers who park most days and drive only for errands |
| Root | Telematics-based scoring during a test-drive period | Safe, infrequent drivers comfortable with app monitoring |
| Mile Auto | Pay-per-mile via monthly odometer photo submission | Privacy-conscious low-mileage drivers who avoid app tracking |
| Clearcover | Flat-rate digital policy, no telematics required | Low-mileage drivers who prefer no usage monitoring at all |
Sources
- plan comparison tools and coverage options
- background reading: patient’s bill of rights
- maximum coverage
- insurance coverage
Frequently asked questions
What is a pay-per-mile car insurance policy?
A pay-per-mile policy charges a fixed base rate each month plus a variable fee for every mile you drive. Drivers with very low annual mileage often pay less than they would on a flat-rate plan, because the bill reflects actual road use rather than an actuarial average.
Does ai car insurance low mileage pricing guarantee savings?
No. Savings depend on what your current insurer charges and how much you actually drive. Drivers who are currently priced as average-mileage customers but drive well below that threshold are the most likely to benefit. There is no universal outcome.
Do these apps track my location?
Metromile and Root collect trip-level data that can include location information. Mile Auto collects only monthly odometer photos and does not use GPS tracking. Clearcover does not use telematics for rate-setting at all. Each app’s privacy policy should be reviewed directly before enrolling.
What happens if I take a long road trip under a pay-per-mile plan?
Your bill for that month will be higher because per-mile charges accumulate with distance. Metromile limits the miles billed per day on some plans, which softens the impact on longer trips, but terms vary by plan and state. This variability is a relevant factor for drivers whose mileage is low on average but inconsistent month to month.
Are these apps available in every US state?
No. All four apps operate in a subset of states, and availability changes as companies expand their footprint. Checking each app’s website for your specific state is the most reliable way to confirm availability before investing time in getting a quote.
Can I add one of these apps on top of my existing policy?
No. These are full replacement insurance policies, not supplemental products. Switching to one of them would replace your current coverage entirely, so comparing coverage limits, deductibles, and exclusions carefully before making a change is important.
Related guides
- Best AI Life Insurance Apps With No Medical Exam
- Best AI Tools for Insurance Claims Adjusters 2026
- a closer look at Root Alternatives: AI Telematics Insurance Apps
- Clearcover vs Root: AI Claims Speed Compared
- Is Root Insurance Worth It? AI Driving Test Tested
- Best Digital Insurance Providers Apps
- Best Car Insurance for New Drivers 2025: Comprehensive Provider Analys
- Best Car Insurance Companies for New Drivers
- Jerry App Alternatives: AI Car Insurance Apps
- Lemonade vs Root: Which AI Insurance App Wins in
- How to Choose Usage-based Insurance